
What are the benefits of sharing secrets as an investor? – Fred Liu
- Fred Liu spent about 60% of his time on existing positions and 40% on new ideas (2021).
- Hayden Capital had owned 30+ positions since inception and owned seven in 2021.
- New positions start at about 5%, with a limit of 15% per position (2021).
- Hayden’s Sea Limited position was about 4% at the time of the 2018 presentation and about 8 to 9% by the following spring.
- Acquiring a customer in China cost about 20 to 30 USD, he says (2021).
You are currently viewing a placeholder content from YouTube. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationSea Limited (SE)
Lazada (Alibaba, BABA) · Grab (GRAB) · GoTo (Gojek, GOTO.JK) · Coupang (CPNG) · JD.com (JD)
Tencent (0700.HK) · Amazon (AMZN) · Zooplus (now private)
What did Hayden Capital gain from publishing its letters?
TL;DR: About 95 out of 100 potential partners are not right for Hayden, he says. Real traction came about two years after the first public letter (2021).
What do the letters bring?
[00:00:00] 
[00:00:35] 
I also recognized that in terms of building an investment management firm, which I mentioned in the last interview, about how we really try to find partners that are very well aligned with us. Most partners out of a pool of a hundred potential people out, there are probably 95% of them that are not going to be right for us. In terms of building an investment firm and getting what we’re doing out into the world, I thought that writing our letters and just making it public would make us very easy to find. It’s surprisingly something that most investment firms don’t do, but I think it’s one of the best tools that an emerging manager has nowadays. A lot of my inspiration from back in the early days was reading other peoples’ investor letters. The reason why it’s named Hayden capital is that I spent a lot of my freshman year inside of Hayden dorm at NYU reading other investors’ letters.
The internet was just starting to come, and people were starting to put their ideas onto the internet. You were starting to get presentations from Ira Sohn or different types of conferences. I got a lot of value out of that and so I always said I’m going to write for myself and put my ideas onto paper. At the same time, they’re going to plant the flag in the ground and allow other people to also learn about what we’re doing and those who resonate can come and find me. There were a couple of other investors who were starting to do that, like John Huber. I remember reading his stuff even before I started Hayden. Hi John, you’re a big inspiration to me! We just really started publishing.
It was probably about two years after we published our first letter and started putting them on the internet before we started getting real traction. As I had more and more people reading them, a lot of people would reach out. I would travel and I would include in our letters what cities I was visiting and tell my readers to let me know if they wanted to grab a coffee. I would have really interesting conversations with my readers. I met a lot of my current network that way. You get differentiated insights where you aggregate all this information together and then you re-distribute it back out into the community through the letters. It creates this virtuous cycle and that’s really what has happened here.
What is also interesting is that because our materials get sent around a bit more widely nowadays, it helps us curate our partner base. Number one, because it reaches the hands in various corners of the world of people who think like us, and they naturally want to engage. They reach out, but also amongst companies too. A lot of companies that we are interested in, or competitors of the companies that we own have started reading our reports. We get feedback that way as well, so it just created this virtuous cycle which is pretty amazing. I honestly don’t think you could have done this as an investment firm 30 years ago or even 20 years ago when the internet was just starting to come about.
I think if you tried to run a hedge fund 20 or 30 years ago in New York, you were probably collecting capital from the same pool of partners. There would probably be 50 or 100 people that would sit within the same circle group, and you would be having dinners with them and meeting them periodically. But, out of those 100 people, probably most of them wouldn’t align with you. If your pool is smaller, you are forced to accept capital that isn’t right for you, so you need to be a little bit more on guard, a little less transparent and a little bit more cautious of how you protect that pool of capital to make sure that your ideas don’t disseminate out and that the churn within your client base is low.
Today, we are able to pick our spots and skim the cream off the top from a global investor base. So, we don’t have those problems and we can be more transparent and more open with our ideas. That creates that virtuous cycle which I think is just amazing. I said in the last interview that I’m still surprised how many investment firms out there are still operating under a model that worked 30 years ago, but probably not today.
Why share ideas publicly?
[00:05:23]
[00:05:38]
So, I have no problem disseminating our information out, even if we’re giving a little bit of our secret sauce. Who cares, we’ve already built our position. The more people that know about how great this company is, the better quality the shareholder base is. If we can upgrade that shareholder base in our own little way, that benefits everyone. It benefits the company, it benefits us, it brings more attention to the stock and maybe it pulls forward some of that valuation. So, I honestly think it’s beneficial for everyone here.
[00:07:06]
What is Fred Liu’s edge and what is too hard?
TL;DR: Internet-based, consumer-facing businesses in the US and Asia. B2B is too hard, and he splits his time about 60:40 between holdings and new ideas (2021).
Where is his edge?
[00:07:25]
[00:07:43]
All investing is pattern recognition. You need to look at enough data points and patterns to formulate your own idea of what works and what doesn’t and how businesses and ecosystems develop. That just takes a lot of time. Our edge isn’t some natural secret sauce. It’s just that we’ve spent a lot of time in that area. That’s really the basis of it.
Why avoid B2B?
[00:08:45]
[00:08:59]
Let’s say you’re a soft SaaS type of business, you have 100 customers. How many people inside of each corporation really use your piece of software and are extremely knowledgeable about it? Maybe like five to ten. So, call it a couple of hundred customers in the entire world who probably have the information and data insights that you’re looking for when you’re trying to do research. Then we have to go find a representative sample of these customers. That’s really tough compared to something like e-commerce or a consumer marketplace where there are probably hundreds of thousands or millions of users. It’s a lot easier to go find the customers who have some insight in how they use the product and get can get feedback on it. Then you can build a representative sample a lot easier. So. I would say that anything that’s B2B is a bit more outside of our circle. It’s also hard to collect this information online, whether you’re talking web scraping or all data or what have you. Just because you know a lot of these habits and how they interact with the product just doesn’t live online in the beginning, so it’s hard to track.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
[00:10:41]
[00:10:49]
How does he split his time?
[00:11:20]
[00:11:31]
What does Fred Liu look for in a new investment?
TL;DR: Four criteria: a strong tailwind, the leader of the pack, great management and a valuation disconnect. Marketplace users order four to five times a month (2021).
Which criteria must an idea meet?
[00:12:14]
[00:12:21]
Number two is that once you spot this kind of tailwind, or what my friend describes as finding a wave. You’re looking for big waves. You also want to find the companies that are going to be leading the pack because certain companies have certain advantages and in the industries that they operate in, tend to benefit from scale and tend to be in the “winner take most” type of market. So, you want to find the companies that have a certain advantage, culture or secret sauce to them that allows them to be at the forefront. As they pull away from the pack, even more advantages accrue to them, such as more data. For instance, the more transactions you see across different geographies, the more you can tailor your inventory and business model around that. Smaller competitors wouldn’t be able to compete with that.
Also, they may have better access to capital due to being able to list first. Because they have a much stronger shareholder base, their cost of capital is lower so they’re able to experiment more with that lower cost of capital. Some of those experiments are going to work and that’s going to propel them even further ahead of their competitors. So, we’re looking for some aspect of that.
Number three is looking for a great management team that is capable of navigating this. In our industries, they’re evolving so rapidly. You don’t need someone to just maintain the status quo and make sure that the business doesn’t die. You rather need someone to innovate and constantly propel the business forward. In this case, it’s kind of like being a surfer on this wave. You see this big wave, but you also need to have the skills to really surf that wave and hopefully when that wave peters out, to hop onto a new one that is equally as large of a tailwind or as large of a wave.
Then lastly is around valuation. We’re looking for some disconnect in the markets. When we typically initiate a position, they’re not very well known in the market. There’s usually controversy and uncertainty in terms of the trajectory of the business and how steep that future earnings or power slope is going to look in the future. We feel, based upon our data points and pattern recognition that we have a differentiated opinion on that. If we are right, we’re actually going to get multiple expansion over the course of that business. So, we think that earnings are going to CAGR higher than what the street expects over the next three, five or ten years. On top of that, as the business gets more certain in the business model, it becomes more evident to people that it’s going to actually be able to be profitable sustainably. You’ll see that multiple also expand on top of that earnings CAGR. So, those are the four things that we’re looking for here.
What signals a strong marketplace?
[00:16:12]
[00:16:23]
If you think about consumer marketplaces, the best analogy that I have for it, and I’ve talked about a little bit is that they’re like self-regulated ecosystems. As the company and as the management, you’re almost like God. You are almost like the government in a sense. You are dictating the rules and setting the laws for what happens inside of this ecosystem that you create but you don’t really control the businesses that move to this ecosystem. Let’s say it’s like a new city. You don’t really control the businesses that come to this new city, and you don’t control the population. This guy decides to immigrate from elsewhere to your new city but you’re setting the rules and making things attractive enough for these businesses and these consumers to then interact with each other. So, whether it’s informal taxes or zero taxes, that’s always great for attracting new people to your new city. Then hopefully they start interacting with each other. People love living there and get a lot more value living there than the cities where they came from and so they aren’t going to move. You can charge them a two or five percent tax but say they get ten or twenty percent more value than the old city where they came from. They still aren’t going to move and they’re going to be happily willing to pay that tax. You’re going to spend that tax revenue creating even a better environment in your city, whether it’s building or upgrading your subway system or building new roads or widening existing roads. You would be attracting even better talent to your city, so that these businesses have great employees to go work for them. These are typically the early signs that we’re looking, even when a city isn’t charging any tax or in the case of a business, any revenue. You can see that the businesses that move there love it and you can see that the inhabitants that move, there love it. They’re interacting with each other, and a lot of transactions are flowing. That’s the basis of an early sign for a consumer marketplace that is what you should look for because that taxation is inevitable because you’re going to have the ability to tax them, and you will. You will recycle that tax revenue to create an even better city which then creates that virtuous cycle effect.
[00:19:13]
[00:19:21]
How does he judge management decisions?
[00:20:11]
[00:20:21]
You want to start with the founding. You want to ask yourself why this business was founded in the first place and what problem were they trying to solve. What value were they trying to create? From the time that they were founded to today, what are the key questions or key friction points that they really had to solve to propel them to where they are today. The only reason we would be interested is that they have something special. So how did they create that special sauce in the preceding five and 10 years and hopefully most of our companies are founder-led, so it’s the same people who started on day one to today. What decisions did they make and looking in hindsight, with the data that you have now, did they make the correct decisions? Even if they made a mistake and made incorrect decisions, given the data that they had at that point in time, say five years ago, did they make the correct decisions with that set of data they had? That’s what we’re looking for you.
You have to, number one, know the company well enough for yourself to have an objective opinion of what was the correct decision and what you would have done as an investor. Then you want to go back and see if management thought similarly to how you would have acted. Then going forward, over the next five years, there are generally one to three different questions or friction points that they need to solve to create a lot of value for this business. You want to see how they are thinking about those questions and as an investor, you probably have an objective opinion of what you would do as a management team. You want to see if the management team aligns and has publicly said this is the direction that they’re moving in. Whether you agree or disagree with them, and sometimes you may disagree, but we want to ask then what information does the management team have that we don’t have access to, that if we had access to that data maybe we would change our opinion.
It’s just a conversation and making an opinion or judgment on whether this management team has navigated the corners well over the past five to ten years.
How does Hayden Capital build a position?
TL;DR: An initial memo of up to 10 pages, a starting position of about 5% and a limit of 15%. He thinks two or three out of 100 companies are great (2021).
How does a position get built?
[00:22:51]
[00:23:06]
Phillip has been producing like 10-page initial memos, so it could be up to 10 pages. We really want to understand the history, how the business is advantaged today, why we think it’s going to continue to be advantaged in the future and what are the one to three key things that they have to get right for this stock to work.
We’re not trying to answer those questions at that point in time. We’re just trying to lay out the thesis and if this happens the stock is going to be a home run. Then we are also trying to answer these questions. We need to consider what pieces of data, who we need to talk to, what data sets we need to buy or what alternative data providers we need to be able to answer this right. That’s the initial memo.
If we decide to move forward on it, we’re going to build a model at that point in time. A model is really a scrap sheet of paper for you to quantitatively put your thoughts on the paper. You’re never going to out-model someone and be able to get an edge, but it’s good to be able to put hard numbers onto a scrap sheet of paper while you’re doing the future analysis. Then over the next couple of months, it’s really around answering those key questions right and that’s where the fun work starts. So, that’s where the primary research takes place. Whether that’s having conversations with people within our network, using certain expert networks, piecing together what competitors are doing and saying, and just understanding how this whole industry is going to evolve over the next five to ten years. Hopefully, by the end of that process, we’ll have a pretty good thesis or understanding of how those couple questions are going to be answered and if it’s beneficial for the company. If it is, and we think this company has a right to win, at that point we’re going to take an initial position in the company. However, our positions are also sized smaller, call it five percent or so, when we initially invest because those questions are really execution-based. They’re based upon how consumer behavior is going to shift, how a certain country’s disposable income may go up. A certain portion of that disposable income goes to a certain type of company, whether it’s e-commerce or what have you, so you have to wait and see if your thesis around that is correct.
As we start to see these KPIs or data points that prove our thesis, that’s when we increase our position over time. While that’s occurring, you have to stay on top of your names, you have to do as much, if not double the amount of work as our initial work during that maintenance phase because we need to monitor our companies very closely and see if that form of addiction actually is taking place. That process can take a couple of months up to a couple of years. As these different KPIs hit, you’re basically flexing up your position. You’re increasing the amount that you’re contributing capital to this position because the business model has de-risked as some of that uncertainty has dissipated.
So, number one, that position probably deserves to be a larger portion of the portfolio because it’s more certain and also your thesis is proven so your future trajectory of this company is probably steeper. The earnings power curve is probably steeper than what the rest of the street expects and so it deserves to gain more capital as well. That process takes you know a couple months to a couple years.
Generally, we will stop building the position when they hit right before that breakeven sustainable type of level. That happens usually within the first three years on investments and hopefully, by that point in time, we will have built a position to about our limit, which is 15%. Then once they hit that sustainable type of level, hopefully, we are very confident in that industry tailwind, their management team, that the company is the leader of the pack and will continue to lead the pack going forward. So, because of that, we’re very comfortable with such a large position size. It’s kind of inevitable by that point in time and then we are just going to allow our capital to compound alongside of this business as they create more value for their ecosystem and their stakeholders for hopefully over the next 10 years plus. We just let it live on within our portfolio and produce returns for our partners at that point.
How do conversations turn into numbers?
[00:28:46]
[00:29:05]
Do street views matter?
[00:29:56]
[00:30:13]
We’re hoping to have a differing data insight. For instance, that a tailwind is going to be larger in our opinion than most other investors expect or maybe there is a number two player within their industry that we think has a right to win and become number one within their industry, but most other investors don’t and so that’s probably priced into stock as well. So, we’re trying to look for differentiation in that sense and we’re trying to compare to what other investors are expecting because it’s probably priced into the stock, and we do want that kind of multiple expansion as our thesis is proven right. On a shorter-term basis, it really doesn’t matter for us.
How long does research take?
[00:31:35]
[00:31:43]
Given our concentrated nature, we probably spend a lot more time than most other funds on each name. I know several funds that my friends work at where they may spend a couple of weeks on a name and honestly in this industry that might be a lot but for us, we’re spending months in the initial phase. Just to establish that initial five percent position and then after that we’re doing it multiples of the maintenance work over the next several years. So, just through that nature of time spent, you’re probably going to have more information than other people out there.
How many businesses make the cut?
[00:32:41]
[00:33:05]
How does he compare new ideas?
[00:33:45]
[00:33:50]
I think if you spent all your time searching for the absolute best 10 companies in this world, that would be a really tough process and you would probably be sitting in cash the entire time because it would take a long time for you to go find those 10 companies. All we’re trying to do is just constantly upgrade the quality of our portfolio. We’re seven years in, and I think we’re at a pretty good place and originally our bar that we needed to beat was cash.
We started with over 60% cash. We took a number of years to get down to low single digits and now our competition is really the worst position in our portfolio. I think that’s an easier way to think about upgrading and comparing good versus great. Then when trying to find the absolute great companies in the world.
How are positions ranked?
[00:35:54]
[00:36:02]
How does Fred Liu judge customer acquisition and capital allocation?
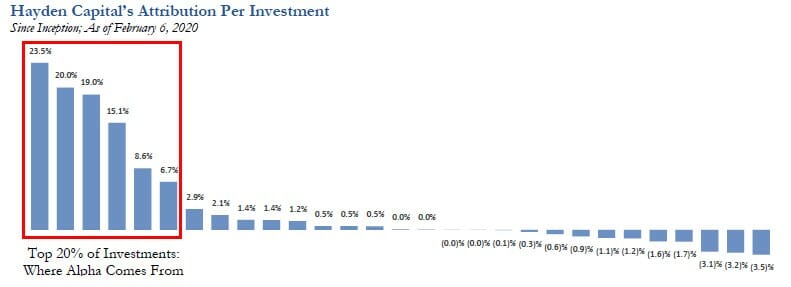
TL;DR: Hayden owned 30 plus positions since inception and seven in 2021. Acquiring a customer in China cost about 20 to 30 USD, he says.
How concentrated is the portfolio?
[00:37:40]
[00:37:53]
Why do high-frequency apps win?
[00:38:35]
[00:39:01]

You open your phone about 10 or 20 times a day. It’s like prime real estate. You’re looking at that app every single day, every single time you open the phone and maybe a certain percentage of the time, you’re opening it you browse through it. It’s a fun experience. It’s like walking into a mall. I think about them like walking into a mall. You walk into it five times a day maybe, you don’t find something 90% of the time but maybe you come across a shop that seems interesting and has some cool item that you didn’t know you needed. You go explore it and you end up buying once a week.
Those consumer acquisition costs then get amortized over the lifetime of that customer and over the lifetime of those purchases. You’re buying five times a month which means you’re buying 60 times a year. It’s amortized over 60 times and because of that and competition, consumer acquisition costs steadily having gone up in the last couple of years. So, it’s gotten more and more expensive to acquire customers. In China now, it costs about 20 to 30 USD to go acquire a customer and that’s why you have this consolidation of these large platforms that are then trying to sell many items because they need to amortize that high CAC.
So, it really depends. To answer your question, it really depends on the business in terms of what makes a good consumer acquisition type of strategy, but I would say the better model is probably the ones that have very high addiction and very high repeat type of customer base because you can amortize that CAC over a very long period of time and when you break it down on a per transaction basis, that means it’s probably in a 1.5USD sometimes. This means that you can also lower your basket sizes, the number of items that consumers need to purchase every single time. When you lower your basket sizes, you increase immediate gratification. That kind of dopamine effect of immediately being able to buy something and having it arrive sometimes on the same day to your door. Then you do it more and more and it creates that virtuous cycle so it depends on the company, but I would say the addiction, high repeat rate type of businesses is more attractive.
Which channel is cheapest?
[00:42:25]
[00:39:01]
How does he judge projects?
[00:43:41]
[00:43:49]
First, they need to underwrite the pool in which we’re operating in. Does this pool of ideas, whether it’s consumer tech in the US or Asia, have attractive returns in the first place? Then among that we are the fishermen fishing in this pool. Are you able to fish the highest return? That process is a judgment of our investment process and so you dive into specific names and when we’re looking at companies, these managers are also allocating capital themselves. They’re allocating into project A, B and C. Maybe they’re building a new factory or choosing to spend a couple hundred million bucks on acquiring new customers or launching a completely brand-new product that has no relation to their current core business. Which one is management choosing and why?
As an investor you need to have enough data yourself and enough of an opinion to then go and say I think they should have chosen project A. I think it’s the highest return type of project based upon my unit economic analysis, conversations I’ve had and on my understanding of where this industry is going. The project they should have chosen was A, but management chose B. So why did they choose B? Then you have that conversation to try to understand why they went in that direction, and this goes back to what I was saying earlier. Maybe they have other data or something else that they’re seeing that you, as an investor, are not. So, maybe we are wrong. We want to understand that decision-making process and the “why” behind it and so at that point it’s like you’re trying to determine if you are right or if management is right. You make a judgment on that and if sometimes management makes the decision that you thought they should have made then that’s easier, but you could both be wrong at the end of the day. Maybe that that’s how you determine if they’re a good capital allocator. You just need to understand the “why” behind it and make that subjective opinion based upon the quantity and bulk of work that you have done up front to reach that conclusion.
Why must culture fit?
[00:46:37]
[00:46:40]
You need a very open-minded management who enables their lower-level employees to go run with those ideas and test if they work in the experiment. That’s a completely different culture. It really depends on the type of company that you’re investing in right.
[00:48:06]
[00:48:19]
How did Hayden Capital build its Sea Limited position?
TL;DR: The position grew from about 4% after the 2018 presentation to about 8 to 9% by the following spring. Trimming starts when expected net returns fall to 10% to 15% (2021).
How did Sea keep its users?
[00:49:00]
[00:49:19]
Purchase. So, they were basically paying people to come live in the city but what we were saying was that once they moved there, they were transacting four to five times a month. They were spending a lot of time inside of these shops. They were providing more reviews for each individual shop owner than where they were listed elsewhere. That means from a shop owner perspective, you’re probably not going to move to a different platform because this is where the bulk of your orders are coming from.
This is a very labor-intensive process because if you understand e-commerce in southeast Asia or just Asia in general, a lot of it is chat based. People ask a lot of questions, so you have to spend a lot of time answering questions. This is where most of the time was spent but there was no monetization, there was no revenues and there was no tax revenue coming in, but you knew that the company’s game plan and their strategy was that once you get people addicted, they are then going to charge a tax. They made that extremely clear.
We also knew through some of the sales materials that we were able to get a hold of hold of that they were communicating to their merchants that they were going to raise their taxes on them very soon. They told them get their products on. So, we have this already addictive kind of foundation to this ecosystem, and we knew that they were going to charge say 1% tax. A 1% tax really isn’t very much if you are providing your sellers with 90% of their business. You’re going to happily be willing to pay for it and they’re selling products where their margins are close to 50%. They will happily pay for that 1%.
So, we invested right before that monetization phase and that was what gave us an early indication that something might work as soon as they raised the monetization over the next six months. We basically saw, number one, none of the sellers left and none of the customers left. In fact, this platform continued to grow above their competitors that were still giving away free money. Actually, what we saw was some of their competitors followed suit in terms of raising prices and raising their taxes. That proved to us that there’s something going on here. There’s a very vibrant sticky ecosystem going on here and so over the following six months we again we had a very small position up front, but we increased our capital committed to that idea because our thesis started to prove itself out. Over the following year, they continued to raise their prices and diversify their base of sellers and the type of products that sold. They started moving up-market into more branded items as opposed to unbranded items and you started seeing people buying very expensive items like Dyson vacuums. They were able to do so because they had built so much trust. So, every step along the journey as they moved upmarket, as they built their logistics, as their shipping times decreased, as they built more trust with consumers and as consumers spent more and more time inside of the app, we continued to increase our position over that period. That’s a relatively newer investment for us. A call like three years or less, but I think it’s a good example of our process for building these positions.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
[00:53:52]
[00:53:57]
What was his edge on Sea?
[00:54:19]
[00:54:26]
[00:55:25]
[00:54:26]
[00:55:25]
[00:55:54]
So, that’s why we have such a large position and why we’re extremely confident. I don’t think that valuation is very taxing at all. We’re actually not expecting multiple compression in this case from here until maturity, but if we had a name that’s say trading at 30x and we think that at maturity, because of competition or whatever other factor, that it should be trading closer to 10x at maturity, we better be very confident in that earnings trajectory. It’s always your headwind that is going to be that multiple compression. Your tailwind is going to be that earnings growth, the net of that is your stock’s return. So, you just better be very confident on that earnings trajectory and that’s going to be a very volatile situation because it’s constantly going to be a tug of war between that earnings growth and that multiple fluctuation. We try to generally avoid those situations. If the net of those starts getting close to say between 10% and 15%, that’s generally when we’re going to start trimming, and if it falls below 10%, which is generally where I view the markets or the S&P type of opportunity cost. We’re probably going to sell out at that position and just follow it and wait for a better entry price to re-go into it. It’s really about the net of those two, the headwind and the tailwind. Usually when we enter a name, we expect multiple expansion and we also expect that earnings CAGR to continue to compound at very attractive rates.
Where can Sea grow?
[00:58:42]
[00:58:46]
What about Sea’s competition?
[00:59:24]
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
How does Fred Liu think about regulators in Asia?
TL;DR: He sees less regulatory uncertainty in Southeast Asia than in China in 2021 and asks Western investors to stay open-minded.
How do government ties help?
[01:00:30]
[00:01:53]
At Sea for instance, Forest always credits the EDB program for jump starting and providing some capital to Garena back in the early days. They hosted the former meetings inside of Shopee headquarters. You can tell that there’s very close ties with the Singapore government. You can go on LinkedIn, and you’ll see posting all the time saying that they’ve just hosted foreign ministers of whatever country so you can tell that they’re pushing in that direction. I’m never going to have an edge in terms of that and have any secret info that’s going to give us some extra alpha. That’s not something that I do but you want to know that at least the company is thinking in that direction and is making a conscious effort towards cultivating these regulators.
How does regulation compare?
[01:03:04]
[01:03:21]
In South East Asia, it’s a little bit different because these companies are very large. They are on the side of the government and pushing these countries, societies and populations in the direction that the governments want them to go. They are not butting heads and creating conflict and because of that, there’s a lot less regulatory uncertainty in South East Asia than elsewhere.
In addition to, because each individual country is relatively smaller compared to China, each individual market is less important to a company like Sea than say China is to Alibaba. You lose China, you kind of lose all of Alibaba’s business. For Sea you lose say the Philippines, it’s not a huge part of their business. So, you cut off one lake and you still have a bunch of other lakes that you can kind of stand upon and so because of that, the companies that operate in southeast Asia have a bit more leverage, especially the larger ones and the world-class ones, over the government regulators than in other larger markets.
Why stay open to innovation abroad?
[01:05:05]
[01:05:17]
How does Hayden Capital deal with volatility and changing markets?
TL;DR: Volatility is the price of the strategy, he says. Tencent returned about 20 times during the value heyday of the 2000s.
How does he deal with volatility?
[01:06:33]
[01:07:21]
Where are the opportunities?
[01:08:04]
[01:08:14]
For instance, people call it the mid-2000s as the “Heyday of Value”, like deep value, and you’re what you traditionally think of as a value strategy. Have you seen Tencent’s returns from 2004 until now or even the late 2000s?
[01:09:25]
[01:09:30]
What these companies’ earnings trajectories are based upon is consumer demand and most consumers don’t even own stocks. They don’t know what’s going on. They just know this is a product that appeals to me. This is what I want. I’m going to spend more of my wallet share on it and the company is going to benefit from that. That’s what you should be looking for. Dig into the actual real economy, not necessarily what other investors are doing, and how multiples are going to fluctuate, especially if you have a longer-term price.
[01:10:45]
[01:10:54]
[01:10:59]
- Spends about 60% of his time on existing positions and 40% on new ideas [00:11:20]
- Writes a memo of up to 10 pages before a 5% position [00:22:51]
- Held seven positions, out of more than 30 since inception (2021) [00:37:40]